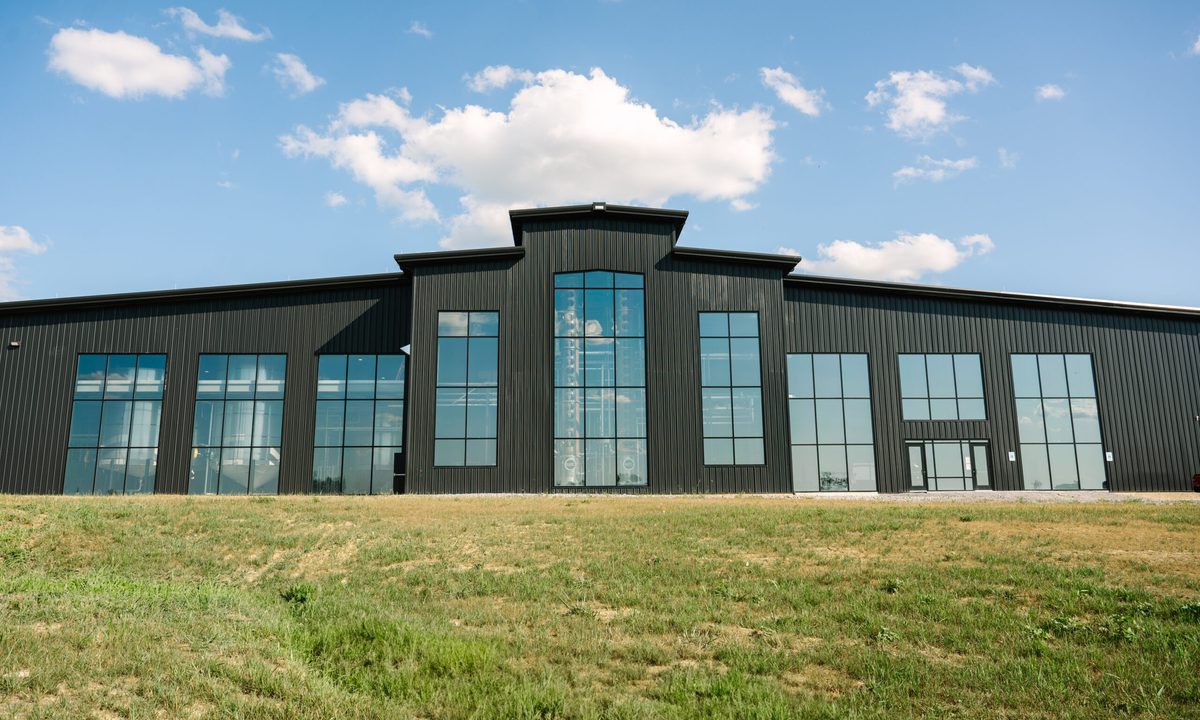
“Be greedy when others are fearful” is a Warren Buffett-ism that’s easier said than done, but Sazerac was apparently paying attention: the company announced today that it’s adding a fourth distillery to its home-state network. The Garrard County Distilling facility in Lancaster, Kentucky, will sit alongside Barton 1792 in Bardstown, The Glenmore Distillery in Owensboro, and of course, the Buffalo Trace distillery in Frankfort.
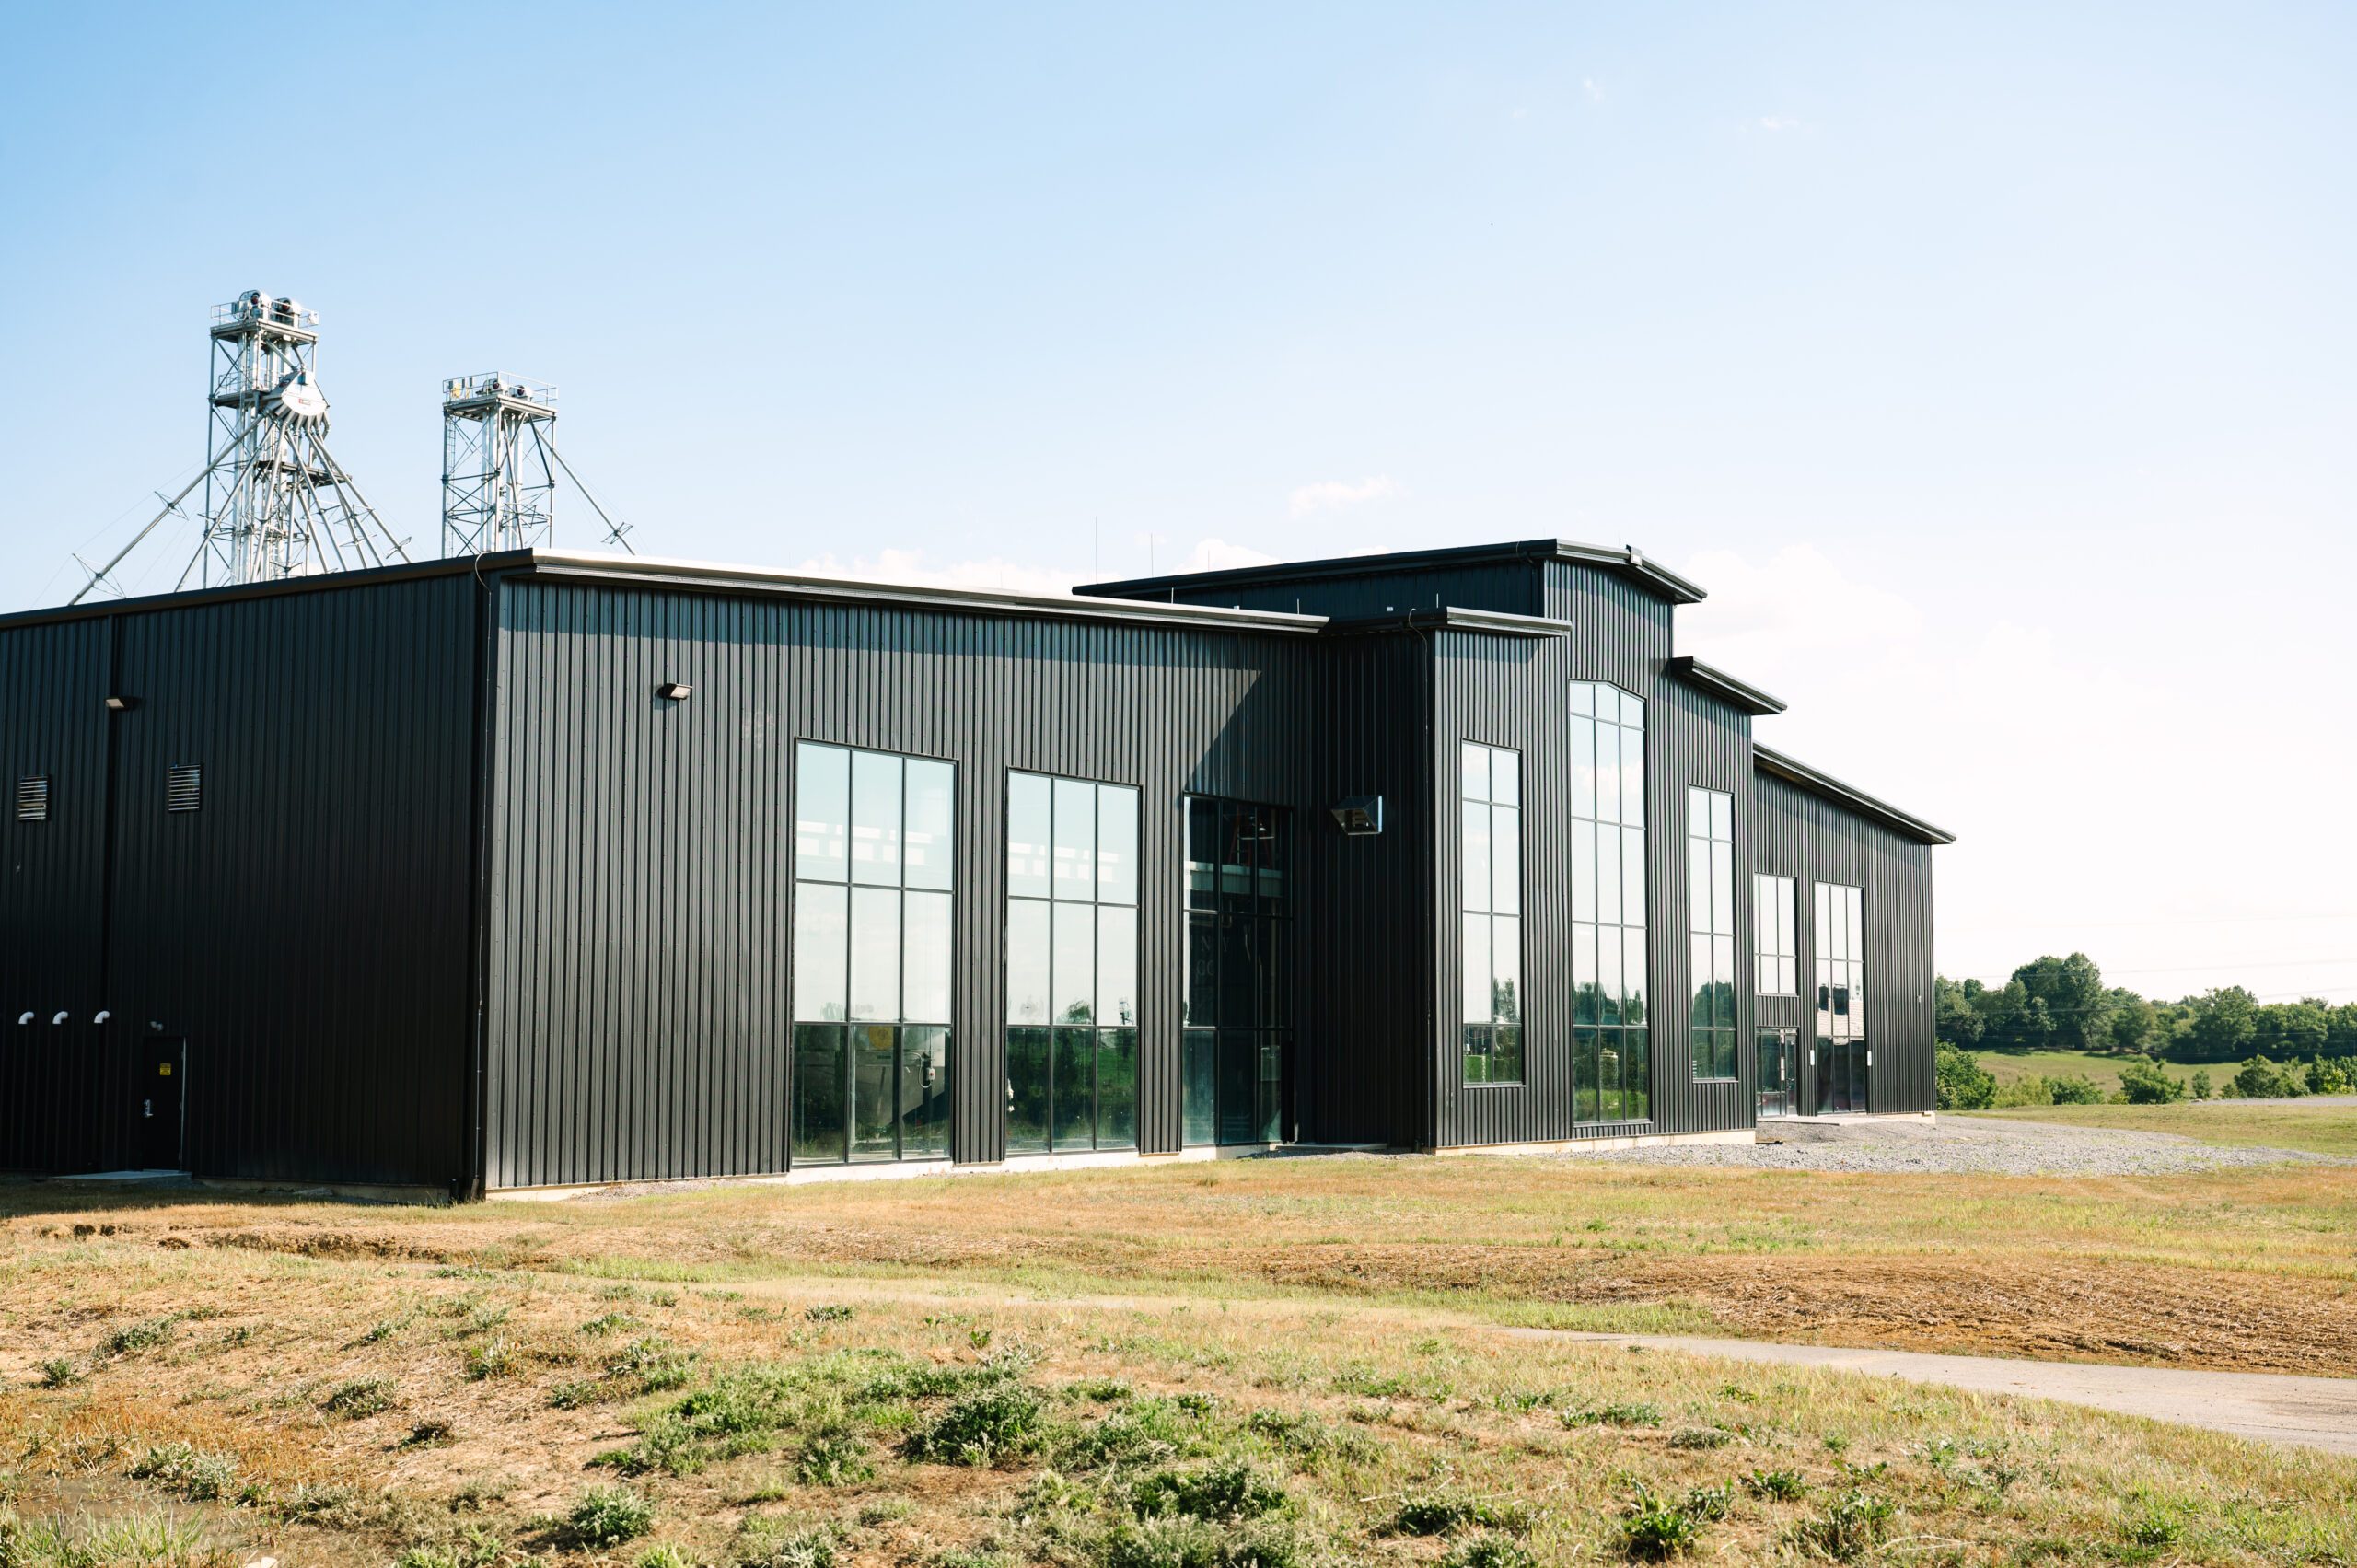
Sitting on roughly 210 acres with two column stills and two 20,000-square-foot barrel warehouses, Sazerac plans to use the existing infrastructure to support its broader production needs, saying that they’ll be hiring additional staff as operations ramp up over time.
“Kentucky has been an important part of Sazerac’s story for many years, and we’re proud to continue investing and growing here,” said Jake Wenz, President and CEO of Sazerac. Nearly 3,000 Sazerac employees now work across its Kentucky operations, per the company.
The acquisition follows a string of major Sazerac investments across the state. They’ve dropped roughly $50 million at Barton 1792 over the past five years, finished a $1.2 billion, ten-year expansion at Buffalo Trace, and plowed approximately $40 million into The Glenmore Distillery since 2020.
The bourbon market isn’t exactly booming
Sazerac’s timing is bold, to say the least. Most of the bourbon industry is doing the opposite of expanding. Jim Beam paused production at its flagship Clermont facility for the entire year, and distillers across the state have cut output sharply as Kentucky warehouses sit on a record 16-plus million aging barrels, a genuine correction after years of boom-era overproduction.
Garrard County itself is a case study in that correction. The distillery filed for bankruptcy in April 2025, barely a year after it opened, and this acquisition is Sazerac buying the facility out of that failure rather than expanding into an active operation.
To be fair, when you have a history like Sazerac, weathering another downturn is almost (almost) business as usual. As a fourth-generation, privately held company with roots stretching back over 400 years, buying distressed assets during a correction is a pretty standard move for a company with that kind of balance sheet and patience.
Whether that pays off the way it has in past cycles is the real question, but it’s a much easier bet to make when you’re not answerable to shareholders demanding quarterly growth.